

CPOS: Tap to Pay Card Reader analysis by Appwee
If you run a small business, sell at occasional events, or simply need a more flexible way to accept card payments, CPOS: Tap to Pay Card Reader is designed around a straightforward idea: use a compatible phone instead of carrying a separate card terminal. I found the appeal easy to understand from the first screen. The app is free, belongs to the Business category, and comes from CPOS, so its main audience is anyone who wants to turn a phone into part of a payment workflow without beginning with dedicated hardware.
That simplicity is also the reason to approach it with realistic expectations. A phone-based card reader can be convenient, but it is not automatically a complete replacement for every checkout system. Your phone becomes the visible point of contact, while the practical success of a payment still depends on the customer’s card or device, the phone’s compatibility, the account and payment arrangements behind the app, and the quality of the connection available at the time. I would recommend trying it before relying on it for a busy sales day.
What to expect before taking a payment
CPOS is not a stock-management suite, an invoicing office, or a full retail platform in disguise. Its identity is much narrower and clearer: it focuses on accepting card payments through a phone. That focus can be a strength for a market seller, mobile worker, independent professional, or small team that does not want to add a traditional terminal to every location.
The store listing shows an average rating of 4.4 from roughly two hundred ratings, with more than one hundred reviews, and the app has passed ten thousand installs. Those figures suggest that the concept has attracted a real audience, while still leaving room for a first-time user to form an opinion based on their own phone, business setup, and payment needs. I would treat the rating as encouraging rather than as proof that every device or transaction scenario will feel identical.
The age classification is Everyone, which makes the app approachable from a content perspective. That does not mean a child is the intended user or that business responsibilities disappear. Handling payments calls for care: check the amount before presenting the phone, keep the customer’s view clear, and avoid rushing through a confirmation just because the interface looks simple.
The current release is version 2.34.0 and requires Android 8.0 or later. That requirement matters if you are using an older spare phone as a dedicated checkout device. Before planning a setup around it, I would check the Android version and make sure the phone is in good working order. A device that technically installs the app but has a tired battery, a damaged screen, or unreliable connectivity is not a dependable payment tool.
Who will get the most from it
I see the strongest fit in businesses where payments happen away from a fixed counter. Imagine a craft seller arriving at a weekend market with a small display and a phone already used for customer messages. Instead of bringing a separate reader for every occasional event, the seller can prepare the phone, open CPOS, enter the sale, and let the customer use a card or compatible device at the phone. The benefit is not only saving space in a bag; it is reducing the number of separate devices that must be charged, remembered, and protected.
It can also suit a self-employed person who visits customers, provided the payment arrangement and phone setup are ready in advance. A repair worker finishing a job, a tutor collecting a fee after a session, or a photographer taking a deposit at a meeting may value the ability to keep the payment step close to the conversation. In each case, the app is most useful when the transaction is occasional, mobile, and simple rather than part of a large queue with complex product options.
I would be more cautious about using it as the only checkout option in a busy shop. A dedicated terminal or established point-of-sale system may be better when several employees need access, when receipts and inventory must connect to one system, or when customers expect a fast, familiar counter process. CPOS can reduce hardware, but it does not automatically replace the wider organization that a mature retail setup provides.
Getting from installation to a first meaningful success
Start with preparation, not with a customer waiting
My advice for a first-time user is to treat setup as a short rehearsal. Install the app on the phone you genuinely expect to use, not merely on a tablet or backup device that may never be present at the point of sale. Confirm that the operating system meets the requirement, charge the phone, and update it before an event or appointment. These steps sound ordinary, but they prevent the most frustrating kind of failure: discovering a device problem while a customer is ready to pay.
Keep the phone’s screen clean and make sure the case does not interfere with the area used for contactless interaction. I would also remove unnecessary distractions from the checkout moment. Silence unrelated notifications, close apps that may slow the phone, and keep the display bright enough for both you and the customer to see what is happening. This is not about making the phone look like a terminal; it is about making the payment step easy to follow.
The app’s free price lowers the barrier to trying it, but “free” should not be confused with “no preparation required.” Payment services can involve account requirements, transaction arrangements, or business checks outside the basic act of installing an app. CPOS is worth testing early so you understand the complete route from opening the app to receiving a successful confirmation. I would not wait until the morning of a market or the end of an appointment to discover which part of that route still needs attention.
Make the first successful action deliberately small
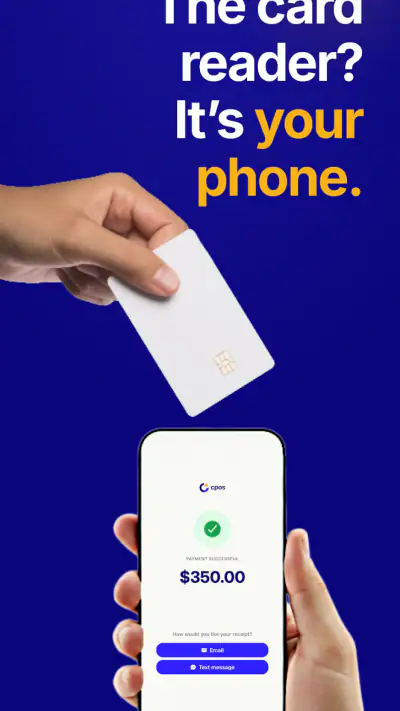
For a first test, choose a simple, low-pressure situation. Have a trusted person act as the customer, use a clearly understood amount, and keep both sides of the phone visible. The goal is not to simulate a complicated sale. The goal is to learn where the amount appears, how the customer knows when to present a card or device, and what confirmation looks like when the process finishes.
This small rehearsal gives you a useful mental checklist. Before starting, say the amount out loud. During the contactless step, avoid moving the phone around unnecessarily. Afterward, check the result in the app rather than assuming that a sound, vibration, or change of screen alone means the payment is complete. That habit is especially important when a customer is in a hurry and the phone is being handed back and forth.
A practical workflow is to keep the product or service discussion separate from the payment confirmation. First agree on what is being purchased and the amount. Then open the payment screen and show the customer the total. Only after the customer has had a chance to verify it should the contactless action begin. This reduces the risk of a wrong amount and makes the interaction feel more trustworthy than silently presenting a phone.
If the first attempt does not work, stay methodical. Check whether the customer’s card or device is being presented in the right place, keep the phone steady, and look for the app’s own status rather than repeating the action immediately. A second attempt made without understanding the first result can create confusion about whether one payment, two payments, or no payment went through. The safest routine is to pause, inspect the confirmation, and communicate clearly with the customer.
Why the phone itself changes the checkout routine
With a conventional card reader, customers generally recognize where to tap and where the payment status appears. With a phone, the person holding the device has a bigger responsibility for positioning and communication. I found that the best approach is to turn the screen toward the customer at the right moment, explain that they should use the phone as the contactless point, and then wait without covering the display.
This is one of the less obvious trade-offs of CPOS. The hardware is simpler because the phone is doing more of the work, but that also means the seller’s phone habits affect the experience. A cracked screen, an awkward case, a nearly empty battery, or a distracting notification can make a short payment feel uncertain. The app may be easy to launch, yet the surrounding physical routine still deserves attention.
Common confusion and the limits I would plan around
A phone reader is not the same as a complete business system
The biggest misunderstanding would be to install CPOS and expect it to replace every tool used in a shop. Its central job is card acceptance through a phone. If your daily work depends on detailed inventory, staff permissions, table management, extensive reporting, printed receipts, or a connected cash drawer, you should compare it with a broader point-of-sale platform before switching.
That does not make CPOS weak. It makes the app more suitable for focused payment collection than for running an entire operation. I would choose it when the payment itself is the main problem to solve. I would look elsewhere when the payment is only one part of a larger workflow that must be synchronized with stock, accounting, customer records, and employee activity.
Do not confuse a successful tap with a completed business record
Another point worth building into your routine is record keeping. A payment confirmation tells you something important about the transaction, but it does not replace your own habit of noting what was sold, to whom, and for which order or appointment. For a small business, a simple reference written down immediately can save time later, especially when several similar payments arrive on the same day.
This is a useful trade-off compared with a traditional register. A phone-based reader can be faster to carry and easier to deploy in different places, but the seller may need to be more disciplined about connecting each payment to the surrounding business information. If your work involves many items or repeated customer orders, consider how you will maintain that link before making CPOS your primary method.
Connectivity and device readiness still matter
Because the app operates on a phone, the quality of the phone environment becomes part of the payment experience. A weak connection, aggressive battery saving, an outdated device, or another app competing for attention can all create friction. I would test the exact phone and location where payments will happen. A successful trial at home does not guarantee the same comfort in a crowded market or a building with poor reception.
For mobile work, carry a charging option and keep a backup payment plan. The backup does not have to be elaborate: another accepted method or a clear process for completing the sale later may be enough for a small operation. This is not a criticism unique to CPOS; it is the reality of putting a business-critical task on a personal mobile device. The convenience is real, but so is the need for preparation.
Privacy and customer confidence are part of usability
Customers may hesitate when asked to tap on a phone because it looks different from a familiar terminal. I would explain the action plainly, avoid touching the customer’s card or phone unless necessary, and let them see the amount and result. Never photograph payment cards or ask for unnecessary card details as a workaround for a failed contactless attempt. A calm, transparent process is more reassuring than rushing to make the technology appear effortless.
The same principle applies to your own phone. Use a lock screen and keep business activity separate from personal conversations where practical. If the phone is shared with family members or used for many unrelated tasks, think carefully about who can access the payment app and when. The app’s Everyone age classification describes its content suitability, not the level of business care required from the owner.
How CPOS compares with the usual alternatives
The most obvious alternative is a dedicated card terminal. A terminal usually feels more purpose-built, can be easier for staff to understand, and may be more comfortable during a long queue. It is also another object to buy, charge, carry, update, and secure. CPOS has the opposite profile: lower equipment overhead and greater mobility, with more responsibility placed on the phone and the person operating it.
A broader point-of-sale application is another alternative. That route makes more sense if you need a catalog, inventory controls, employee accounts, or detailed sales reporting in the same environment. CPOS is more appealing when those features would be unnecessary weight. I would not select a large retail system merely because it sounds more complete if all you need is a reliable way to collect a straightforward card payment while working away from a counter.
Cash remains relevant for customers who prefer it or when technology fails, while bank transfers may suit some professional services. Neither option provides the same immediate contactless experience. The sensible choice depends on your customers and your setting. For me, CPOS works best as a convenient primary method for suitable transactions or as one part of a small, sensible payment mix, rather than as a promise that every other method can be discarded.
Three habits that make the app more useful
- Rehearse the complete payment path: do not stop after installation. Practice entering an amount, presenting the phone, recognizing the final status, and recording the sale in your normal business notes.
- Design the customer-facing moment: keep the amount visible, tell the customer exactly when to tap, and hold the phone steady. This removes uncertainty that a standard terminal normally hides through its familiar shape.
- Separate convenience from resilience: use the phone reader to reduce equipment, but keep it charged and maintain a fallback method. The fewer devices you carry, the more important the remaining device becomes.
These habits are more valuable than simply memorizing where to press. They address the parts of mobile payment that can surprise a first-time user: the physical positioning, the confirmation discipline, and the need to connect a digital payment with ordinary business records.
My recommendation after using it as a first-time seller
CPOS makes sense if your main goal is to accept card payments without committing to a separate reader for every mobile or occasional sales situation. The free download and focused purpose make it easy to investigate, and the existing audience gives the app a reasonable starting level of confidence. I especially like the idea for independent workers and small sellers who already carry a capable Android phone and want a lighter setup.
I would not recommend relying on it blindly for a high-volume operation, a complex store, or a business that cannot tolerate a phone, connection, or battery problem. In those cases, a dedicated terminal or full point-of-sale system may justify its extra equipment because it offers a more specialized working environment. CPOS is not the right answer simply because it removes hardware; the right answer depends on whether your business benefits more from portability or from a wider set of checkout controls.
For a reassuring first step, install it well before your next real sale, prepare the phone, and complete a controlled test with someone you trust. Pay attention to the amount display, the customer’s tapping position, the confirmation screen, and your own record-keeping routine. If that sequence feels clear and repeatable, you have learned the most important thing: whether this phone-based approach fits your actual day, not just the idea of it.
My final view is positive but measured. CPOS is strongest when it stays in its lane: a portable card-payment tool for simple, mobile transactions. It can make a small setup feel lighter and more adaptable, but the best results come from pairing the app with a prepared device, clear customer communication, and a backup plan. If that matches the way you work, it is worth trying; if you need a complete retail command center, choose a solution built for that broader job instead.
Gallery
CPOS: Tap to Pay Card Reader Pros and Cons
- Turns compatible phones into a convenient mobile card reader.
- Supports contactless payments without requiring a separate terminal.
- Useful for small businesses
- freelancers
- and pop-up sellers.
- Can reduce hardware costs for occasional payment collection.
- Portable setup works well for markets
- events
- and mobile services.
- Requires an NFC-enabled device and compatible operating system.
- Payment availability may vary by country
- bank
- and supported card network.
- Transaction fees can reduce earnings
- especially for small purchases.
- Phone battery or connectivity issues may interrupt payment processing.
- Some features may require account verification or a compatible merchant plan.
CPOS: Tap to Pay Card Reader Frequently Asked Questions
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale application designed to help businesses accept card and contactless payments using a compatible smartphone or tablet. Instead of requiring a traditional card terminal, the app can use the device’s NFC capabilities for supported tap-to-pay transactions. Availability, supported payment methods, and account requirements may vary by country and provider.
What devices are compatible with CPOS: Tap to Pay Card Reader?
Compatibility depends on the operating system, device model, NFC hardware, and the payment service connected to CPOS. Android users generally need a device with NFC and a supported Android version, while iPhone support can depend on the specific Tap to Pay service and region. Before downloading, check the app listing and official requirements to confirm that your phone or tablet is supported.
Do I need a merchant account or payment provider to use CPOS?
Yes, a payment or merchant account is normally required before you can accept real customer payments through CPOS. The application is not usually a standalone bank account or payment processor; it works with an approved provider that handles authorization, settlement, verification, and transaction fees. Registration may require business information, identity checks, and banking details.
Is CPOS: Tap to Pay Card Reader safe for processing payments?
CPOS is intended to process payments through secure payment infrastructure, but the overall security also depends on the connected provider, your device, and how the account is managed. Keep the operating system and app updated, use a screen lock, avoid rooted or modified devices, and never share login credentials. Review transaction confirmations and provider policies before using it with customers.
Are there transaction fees or limitations when using CPOS?
Using CPOS may involve transaction fees, account charges, payout costs, or other pricing set by the payment provider rather than by the app itself. Tap-to-pay acceptance can also be limited by supported card networks, contactless rules, transaction amounts, offline availability, and regional regulations. Read the provider’s current pricing and terms carefully before relying on CPOS for daily sales.














